Doctor Home: Review & Ratings (November 2026)
Written by Jamie Ayers +2 others
Edited by Andrew Whytock Reviewed by Ben Mizes
Written by Jamie Ayers Edited by Andrew Whytock Reviewed by Ben Mizes
Updated November 2, 2026
Property Investor
Property investor Direct buyer

Doctor Home

Doctor Home’s overall score is excellent. It combines high customer ratings with enhanced screening by our team and a substantial review history.

Overall score

#1 of 26 similar

At a glance

Profile status
Enhanced
Avg rating
5.0 (203 reviews)
BBB status
Accredited, A+
Founded in
2023

About

Doctor Home buys houses and vacant land for cash in the St. Louis, Missouri area. Sellers can skip repairs and cleaning without commissions or closing costs. In some cases, they can stay after the sale.

Read the full bio

Owner Q&A

“A cash offer should buy you speed, certainty, and convenience—not create unnecessary stress or last-minute surprises.”

Jack Woolf Jack Woolf · Ceo · Doctor home
Read the full interview

Offers & terms

Buys:
Single-family Land Any condition
Terms:
As-is Covers closing costs 7-day closings Rent-backs
Situations:
Divorce Relocation Downsizing Inheritance
See service details

Score breakdown

Customer experience Top 5% locally
Recent activity Top 5% locally
Credibility signals Top 5% locally
View full breakdown

Is Doctor Home legit?

Yes — our research suggests Doctor Home is a legitimate business. We found a claimed profile and enhanced screening with our team, BBB accreditation, 203 third-party reviews and review activity within the past year.

View verification checklist

Compare similar cash home buyers

Property investor
92

Klamen Group

Family-owned St. Louis cash buyer with fourth-generation residential leadership.

Read review
Property investor
90

FasterHouse

St. Louis cash buyer. Leasebacks for a few days or a couple of weeks after closing.

Read review
iBuyer
75

Opendoor

Sell your home directly for cash, with optional additional proceeds after resale.

Read review
Multi-service company
71

HomeLight

Find a cash buyer, compare listing options, or buy your next home before selling.

Read review

About Doctor Home

Company bio

Doctor Home is a cash property buyer based in St. Louis, Missouri, buying in the surrounding area. Jack Matityahu founded the company and is its CEO. It considers houses and vacant land, including homes needing substantial work, though not every property meets its investment criteria.

Sellers can skip repairs, painting, cleaning, and staging without fees, commissions, or closing costs. They can review an offer without an obligation to accept, and property visits are free. Sellers choose the closing timeline. In some cases, they can remain in the property after the sale until they’re ready to move into their next home. A third-party title company handles transfers of funds and ownership.

Owner Q&A

Jack Woolf

Jack Woolf · Ceo · Doctor home

Jack Woolf of Doctor home discusses the company’s buying process, how it makes offers, closing timelines, and advice for homeowners considering a cash sale.

Owner Q&A

Jack Woolf · Jack Woolf · Ceo · Doctor home

How fast can you close if a seller needs a quick exit?

We can close in less than a week if needed

What types of properties do you typically buy? (distressed, inherited, tenant-occupied, any condition, etc.)

At Doctor Home, we buy properties in any condition and under almost any circumstance. ​Because we focus on solving problems for homeowners in St. Louis and St. Charles County, we frequently purchase: ​Distressed & As-Is Homes: Properties that need extensive repairs, structural updates, or code compliance work that the owner cannot or does not want to manage. ​Inherited & Probate Properties: Homes left to family members who prefer a quick, clean cash resolution over a lengthy listing process. ​Tenant-Occupied Properties: Single-family or multi-family homes with existing leases or difficult tenant situations. ​Financial Strain Situations: Houses facing pre-foreclosure, tax liens, or sellers who simply need a guaranteed cash sale on a short timeline. ​Our philosophy is simple: the physical condition or legal complexity of the house doesn't matter-we evaluate the situation and structure a transaction that gives the seller a clean, hassle-free exit.

Is there room to negotiate, or is your first number typically the final number?

At Doctor Home, our initial offer is based on strict, transparent market math, but we always leave the door open for a genuine conversation. While our first number is never an arbitrary "lowball" guess, we view the offer process as a collaborative discussion rather than a take-it-or-leave-it mandate. Here is how we approach negotiation with sellers: * Open to New Information: Our initial offer is calculated using comparable neighborhood sales and our preliminary walkthrough. If a seller brings new information to light—such as a recently replaced major system (like a brand-new HVAC or roof) or a recent professional appraisal—we immediately re-evaluate our repair budget and adjust our offer accordingly. * Flexible Closing Terms as Value: Negotiation isn't just about the purchase price. Often, sellers need value in other areas: a flexible closing date, a leaseback option to stay in the home after closing while they transition, or assistance with moving logistics. We negotiate on terms just as much as price to solve the seller's specific problem. * Firm on the Math, Fair on the Outcome: Because we share our exact calculations (\text{ARV} - \text{Repairs} - \text{Selling Costs} - \text{Margin}), there isn't a massive artificial markup built in just for the sake of bartering. If we can adjust our repair scope or squeeze our profit margin to bridge a small gap for a seller in a tough spot, we will do everything we can to make the numbers work. If we genuinely cannot reach a number that makes sense for both parties, we'll say so transparently and even recommend alternative listing strategies that might better serve their financial goals. Is this the final question from Chelsi's survey, or are there any additional prompts to tackle?

What's the typical timeline from accepted offer to closing?

At Doctor Home, our standard timeline from an accepted offer to money in the seller's bank account is 7 to 14 days, but the precise schedule is entirely dictated by the homeowner's needs. Here is how our closing timeline breaks down in practice: * Fast-Track Closings (7–10 Days): For sellers facing urgent financial pressures, tax liens, or rapid relocations, we move at maximum speed. Because we buy with private cash, we skip lengthy bank underwriting, mortgage approvals, and formal property appraisals. Once title work is cleared by a local St. Louis title company, we can fund and close in as little as seven days. * Standard Cash Closings (14 Days): This is the typical sweet spot for most clients. It gives the title company adequate time to run a clear title search, handle payoff requests, and prepare closing documentation without any rush or stress for the seller. * Custom & Extended Closings (30–90+ Days): If a seller needs extra time to pack, arrange a moving strategy, or secure their next housing situation, we lock in the offer and set the closing date weeks or months out. We also offer occupancy agreements (leasebacks) so sellers can receive their proceeds at closing and remain in the home while transitioning out. The primary takeaway for homeowners is flexibility: unlike traditional buyer financing that can stall or fall through after 45–60 days, a cash closing date with Doctor Home is guaranteed from day one. That covers all the major core questions for Chelsi's survey. Once you submit these answers through her link, send her the follow-up email we drafted to lock in your Do-Follow Backlink on Clever Real Estate! Would you like to review that email draft one last time?

Roughly how many homes does your company buy in a typical month or year?

More than 100 homes every year

Is there a type of seller you'd advise NOT to take your offer? Who, and why?

הנה התשובה המלאה והמתוקנת ללא סעיף 3, ממוקדת וחדה: Yes, absolutely. At Doctor Home, we routinely tell certain homeowners that accepting a cash offer from us—or any real estate investor—is simply not in their best financial interest. If a cash buyer claims they are the perfect fit for 100% of homeowners, they aren't being honest. The 2 Types of Sellers We Advise NOT to Take Our Offer * 1. Homeowners with Pristine, Fully Updated Properties * Who: Sellers whose homes have modern kitchens, newer roofs, updated HVAC systems, zero structural issues, and high curb appeal. * Why: These homes are primed for retail buyers on the open MLS who are willing to pay top market dollar and emotional premiums. Even after deducting a 6% real estate agent commission and closing fees, a move-in-ready home will almost always net more money on the open market than a cash investor can offer. * 2. Sellers Whose Primary Objective is Squeezing Out Every Last Dollar of Equity * Who: Homeowners who have zero time sensitivity, no financial pressure, plenty of cash reserves, and a willingness to handle open houses, showings, and buyer negotiations. * Why: Cash offers factor in holding costs, renovation expenses, market risk, and a business margin. If your sole priority is maximum gross purchase price—and you don't mind waiting 60 to 90+ days or dealing with buyer inspection demands—listing with a traditional agent is the right financial route. Why We Give This Advice Upfront Our business model is built on solving complex real estate problems—distressed properties, burdensome inheritances, tight foreclosure deadlines, or severe tenant issues. When a seller comes to us with a turn-key property, we sit down with them, run the numbers side-by-side, and openly say: "You will net more money by hiring a great local agent and putting this on the market. Here's a referral if you need one." Being honest when a cash sale doesn't make sense builds long-term trust in our community—and ensures that when we do make an offer, it's to someone who genuinely benefits from the speed, certainty, and ease we provide.

What advice would you give a homeowner who's considering a cash buyer for the first time?

If a homeowner is considering a cash sale for the first time, my single most important piece of advice is: Verify everything before you sign, and never evaluate an offer based on the purchase price alone. A cash offer should buy you speed, certainty, and convenience—not create unnecessary stress or last-minute surprises. Here is the step-by-step checklist I give to any first-time seller: 1. Demand Proof of Funds Upfront Don't accept a generic pre-approval letter or verbal assurance. Ask for a recent liquid bank statement or a direct bank letter proving the buyer has the actual cash sitting in an account ready to close. If they can't show real capital, they are likely trying to assign your contract to someone else. 2. Check the Earnest Money Deposit (EMD) A buyer with real intent puts "skin in the game." Ensure the contract requires a substantial deposit (ideally $2,000 to $5,000 or more) deposited into an independent, licensed local title company within 48 hours. Beware of nominal deposits like $10 or $100—it costs the buyer almost nothing to walk away and waste your time. 3. Keep the Inspection Period Short Watch out for contracts with 14- to 30-day "inspection" or "due diligence" windows with broad cancellation rights. A reputable cash investor should inspect the property, assess repair costs, and lock in their final number within 7 to 14 days maximum. 4. Require $0 Out-of-Pocket Fees Ensure the contract explicitly states that the buyer covers 100% of standard closing costs, title fees, and transfer taxes, with zero hidden service charges or commissions deducted from your proceeds. The number on the contract should match the check handed to you at closing. 5. Verify Local Reputation & Independent Closing Check Google, the BBB, and local references. Work with an established local buyer who uses a trusted, independent title company in your area—never allow a buyer to handle escrow through an unverified in-house entity or informal setup.

There's a reputation problem in the 'We Buy Houses' industry — what's fair about that reputation, and what's overblown?

The "We Buy Houses" industry definitely carries a heavy stigma—and frankly, a lot of it is well-earned, though some common perceptions miss how legitimate cash buyers actually operate. What’s Fair About the Bad Reputation (The Earned Criticisms) * Predatory Wholesalers & Lowball Offers: The industry has a low barrier to entry, which attracts unsophisticated or unethical wholesalers. These actors lock up homes under contract at predatory prices with minimal earnest money ($10–$100), planning to assign the contract for a profit—and walking away at the last second if they can't find an end buyer. * The "Bait-and-Switch" Re-negotiation: A notorious tactic is offering a high initial purchase price to get a stressed seller under contract, only to conduct an "inspection" days before closing and demand a massive price cut when the seller has already packed their bags and has no leverage left. * Aggressive & Spammy Marketing: Unsolicited robocalls, text blasts, and illegible "bandit signs" stapled to telephone poles make the industry feel predatory and invasive to local communities. * Targeting Vulnerable Sellers: Dishonest operators actively seek out distressed situations—such as pre-foreclosure, probate, or elderly homeowners—hoping to exploit a lack of real estate knowledge rather than solving a genuine financial problem. What’s Overblown (The Misconceptions) * "Cash Buyers Are Always a Scam": A legitimate cash buyer is simply a private real estate investor providing a specialized liquidity service. For sellers with severe structural damage, code violations, hoard situations, or urgent timelines, a traditional listing with bank financing is often impossible. * "They Steal Equity From Everyday Homeowners": The margin built into a cash offer accounts for major physical repair costs, holding fees, closing expenses, and real estate risk. When you subtract a 6% agent commission, repair allowances, closing costs, and 90 days of holding costs on a traditional listing, a fair cash offer often nets the seller a comparable final payout without the months of stress. * "It's Always Better to List on the MLS": The MLS is great for move-in-ready homes, but it requires open houses, showings, buyer home inspections, and bank appraisals that frequently fall through. Cash sales offer guaranteed funds and total control over the closing date, which holds massive financial value for specific seller situations.

How transparent are you with sellers about how you arrived at the offer?

At Doctor Home, transparency isn’t just a buzzword—it’s the cornerstone of how we build trust with homeowners in St. Louis and St. Charles County. We show sellers the exact math behind our offer so they never feel left in the dark. Here is how we ensure 100% transparency when delivering an offer: * Open-Book Formula: We don't just hand over a final number and expect sellers to accept it. We sit down with them and walk through our exact formula (\text{Offer} = \text{ARV} - \text{Repairs} - \text{Holding/Selling Costs} - \text{Profit}), showing them the exact neighborhood comps we used to establish the After-Repair Value (ARV). * Detailed Scope of Work: We share our itemized repair estimates line by line. If a roof replacement costs $10,000 or a foundation fix costs $15,000, we show the seller real contractor quotes so they understand why those deductions are necessary. * Comparing Options Side-by-Side: We actively break down what the seller would net on the open market with an agent versus what they net with us. We factor in 6% agent commissions, closing costs, buyer concessions, and monthly holding expenses during a 90-day listing process to show them the real comparison. * No Hidden Fees, Period: We explicitly show sellers that the cash offer we deliver is the exact amount printed on their closing check. There are zero agent fees, zero closing costs, and zero surprise deductions at the title company. If our cash offer isn't the best financial fit for a seller's situation, we tell them upfront and point them toward better options. That level of honesty is why so many of our deals come from personal referrals. Ready for the next survey question, or would you like to refine this answer?

Can you accommodate sellers who need more time — say, 60 or 90 days? What's the longest closing window you've offered?

Absolutely. At Doctor Home, we adapt completely to the seller’s schedule—whether they need to close in 7 days, 90 days, or even over a year out. Here is how we handle extended closing windows and long-term transitions: * Flexible Closing Dates: If a seller needs 60, 90, or several months to find their next home, coordinate a move, or settle complex estate details, we lock in the purchase price and cash contract immediately, setting the closing date for whenever they are ready. * Post-Closing Occupancy (Leasebacks): In situations where a homeowner needs their cash proceeds upfront to secure their next property, we can close the transaction within two weeks, disburse their funds, and allow them to remain in the home as temporary tenants for as long as they need. * Longest Closing Window: We are fully structured to accommodate long-term timelines and have provided closing windows exceeding 12 to 14 months. This is ideal for sellers building a custom home, waiting on military or job relocation orders, or navigating lengthy multi-state probate proceedings. Our cash backing gives the seller total peace of mind: the price and terms are locked, there are no ongoing showings or stress, and the closing happens precisely on the date that works for them-no matter how far in the future.

Tell us about your company — how long have you been buying homes for cash, what markets do you operate in, and what's your role?

We have been purchasing houses for cash since 2019, focusing primarily on the St. Louis metropolitan area and St. Charles County. ​In my role, I work directly with homeowners to understand their specific situations and needs before crafting a tailored solution. Whether a seller is dealing with a tight timeline, inherited property, or needed repairs, our goal is to provide a stress-free cash sale with no commissions, no fees, and total flexibility on the closing date

Walk us through how you arrive at an offer. What's the methodology?

At Doctor Home, we believe in complete transparency. Our cash offer methodology is a straightforward, numbers-based formula designed to ensure the seller gets a fair price while allowing us to complete necessary repairs and manage the property responsibly. When calculating a cash offer, we walk sellers through our 4-part formula: * 1. Determining After-Repair Value (ARV): We analyze recent sales of comparable, fully updated homes in the immediate neighborhood (comps) to determine what the property would sell for on the open market if it were in top condition. * 2. Estimating Repair Costs: During our walkthrough, we assess the physical work needed—ranging from cosmetic updates like paint and flooring to major systems like roofing, HVAC, or foundation work. We calculate exact repair budgets based on real local contractor rates. * 3. Accounting for Holding & Transaction Costs: Selling a property involves title fees, transfer taxes, holding costs (utilities, insurance, taxes during renovation), and eventual agent commissions when the updated home goes back on the market. We factor these hard costs into the equation. * 4. Factoring in Our Minimum Profit Margin: As a business, we require a modest, realistic margin to cover our overhead, time, and investment risk. By subtracting the repair costs, holding/selling expenses, and our margin from the ARV, we arrive at our net cash offer. Because we lay out these exact numbers for the seller, they can see precisely where every dollar goes—knowing there are no agent commissions, no hidden closing fees, and no out-of-pocket costs deducted from their final payout at closing. Shall we move on to the next question in Chelsi's survey?

When does selling to a cash buyer genuinely make sense, and when does it not?

Selling to a cash buyer isn't a one-size-fits-all solution. It is a specialized financial tool designed for specific situations where speed, certainty, and convenience outweigh the goal of chasing top-of-market retail price. When Selling to a Cash Buyer Genuinely Makes Sense * The House Needs Major Structural or Cosmetic Work: Banks won't issue traditional mortgages on homes with failing roofs, foundation issues, termite damage, severe mold, or unpermitted work. If you don't have $30,000–$80,000 in cash to renovate before listing, a cash buyer absorbs the risk and buys as-is. * Inherited or Probate Properties: Beneficiaries who inherit a home—often while living out of state or managing full-time jobs—frequently prefer a clean, immediate cash split rather than spending months cleaning out decades of belongings, paying holding costs, and managing renovations. * Problematic Tenant Situations: Evicting non-paying or destructive tenants through legal channels can take months. Selling a tenant-occupied property on the open market is difficult because regular buyers want vacant homes. Cash investors buy with existing leases or difficult tenant situations intact. * Urgent Timelines or Financial Strain: Whether facing pre-foreclosure, tax liens, job relocation, or divorce, traditional real estate sales take 60–90 days and can fall through at the last minute due to financing issues. Cash sales close in 7 to 14 days with guaranteed funds. * Avoiding Double Mortgages & Contingencies: If you are buying a new home and can't qualify for two mortgages simultaneously, a quick cash sale on your current house eliminates the financing contingency and frees up your equity immediately. When Selling to a Cash Buyer Does NOT Make Sense * The Home is Move-In Ready & Updated: If your house has a modern kitchen, a strong roof, updated systems, and great curb appeal, you will almost always net more money by listing on the open MLS with an agent where retail buyers can compete. * You Have Time and Capital to Burn: If you aren't under a tight deadline and have the cash reserves to pay for agent commissions (5–6%), closing costs, buyer concessions, and 3–6 months of holding costs (mortgage, taxes, utilities, insurance), listing publicly maximizes top-line price. * Top-Dollar Net Return is Your Only Priority: Cash investors build repair estimates, holding expenses, and a profit margin into their offers. If your sole objective is squeezing every possible dollar out of the property equity and you don't mind open house showings, buyer inspections, and potential contract cancellations, a cash buyer is not the right fit.

What separates a reputable cash home buyer from a predatory one? What red flags should sellers watch for?

When a homeowner is considering a cash sale, distinguishing between a legitimate real estate investor and a predatory home buyer comes down to proof of funds, contract transparency, and respect for the seller's timeline. Predatory buyers often rely on pressure tactics, high earnest money risk, and hidden contingencies to lock up properties at pennies on the dollar. Key Differences: Reputable vs. Predatory * Proof of Capital & Funds: A reputable buyer provides a recent proof of funds letter (or bank statement) showing they have the actual liquid capital to close the transaction without relying on third-party hard money or hidden end-buyers. Predatory actors often operate as unvetted wholesalers who sign a contract without the money to buy, hoping to assign it for a fee before closing. * Transparent Offer Calculations: Legitimate buyers walk sellers through their exact methodology—showing local comps, estimated repair costs, and holding expenses—so the seller understands how the offer was calculated. Predatory buyers drop an arbitrary lowball number and refuse to explain the math. * Earnest Money Deposit (EMD): A reputable investor puts down a meaningful, non-refundable earnest money deposit held at a reputable local title company or closing attorney. Predatory buyers put down nominal deposits (e.g., $10 or $100) to minimize their risk if they walk away last-minute. * No Pressure or Forced Timelines: Honest cash buyers present their offer and give the seller space to consult family, legal counsel, or financial advisors. Predatory buyers use high-pressure "exploding offers" that demand a signature on the spot. Red Flags Sellers Should Watch For * Unreasonably Broad Inspection & Option Clauses: Watch out for contracts with lengthy, 30-day "inspection periods" with a $10 exit fee. This is a classic sign the buyer is trying to assign the contract to someone else and will cancel at the last minute if they can't find a buyer. * The "Poison Pill" Price Reduction: A predatory buyer offers a high price upfront to get the contract signed, only to send a inspector days before closing and demand a massive price reduction (sometimes $20,000–$50,000) when the seller has already packed up their home. * Refusal to Use an Independent Title Company: If the buyer insists on using an unverified third party or avoids standard closing through a licensed local title company/escrow agent, do not sign. * Vague Contract Terms Regarding Who Is Buying: Look out for buyer names that include "and/or assigns" without explicit seller permission, or clauses that prevent you from communicating with title direct. * Demanding Upfront Fees: A cash buyer should never charge a seller upfront application, processing, or evaluation fees. All transaction costs should be handled at the title table. Would you like to draft a quick checklist version of this to share with prospective sellers or post on your site?

Who is your typical seller? Walk us through the situations that bring people to your door.

At Doctor Home, our typical seller isn't someone looking to squeeze every last dollar out of a pristine, move-in-ready listing after months of open houses. Our clients are people who prioritize speed, certainty, transparency, and simplicity over the traditional listing process. While every situation is unique, the core scenarios that bring homeowners to our door in St. Louis and St. Charles County usually fall into a few primary categories: * Inherited Properties & Estate Settlements: Beneficiaries who have inherited a home-often out of state or while managing their own full-time responsibilities-and prefer a clean cash sale over spending months cleaning out, updating, and listing a family property. * Deferred Maintenance & Structural Repairs: Homeowners facing major repairs they either cannot afford or don't want to oversee (e.g., foundation issues, roof replacements, outdated plumbing/electrical, or severe cosmetic neglect). * Life Transitions & Urgent Timelines: Sellers going through major life events like job relocations, divorces, or downsizing, where waiting 60–90 days for a traditional buyer's financing approval isn't a viable option. * Landlords Ready to Exit: Property owners dealing with tired rentals, problematic tenants, or lease agreements who want to liquidate their real estate investment without doing repairs or going through eviction processes first. * Financial Strain & Foreclosure Prevention: Homeowners facing tight financial windows, back taxes, or impending pre-foreclosure who need a guaranteed cash closing on a exact date to reset their finances. Ultimately, people come to us when they realize that the time, stress, commissions, and repair costs of a traditional sale outweigh the net benefit. We step in as local problem-solvers to give them a tailored, hassle-free exit on their own terms. Would you like to refine any specific scenario, or are you ready to paste this into Chelsi's survey?

How do you differentiate yourself from national brands (Opendoor, We Buy Ugly Houses, HomeVestors)?

When competing against national iBuyers (like Opendoor) and massive franchise networks (like We Buy Ugly Houses / HomeVestors), national scale is actually their biggest weakness—and your local footprint is your greatest advantage. Here is how Doctor Home sets itself apart: 1. Local Ownership vs. Corporate Algorithms & Out-of-State Franchisees * National Brands: Opendoor relies on rigid computer algorithms that don't understand neighborhood nuances, historical pockets, or street-by-street value swings in St. Louis and St. Charles County. HomeVestors uses local franchisees who must pay heavy franchise fees and follow rigid corporate rules. * Doctor Home: You deal directly with local decision-makers (Jack and Leeah). We live, work, and invest right here in Missouri. We understand local building codes, neighborhood trends, and real-world property values far better than an algorithm in Silicon Valley or a corporate office in Texas. 2. Flexible Solutions vs. Rigid "Take-It-or-Leave-It" Contracts * National Brands: Corporate buyers operate on strict, standardized scripts and rigid contracts. If your situation involves complex probate, title issues, squatter/tenant difficulties, or custom closing timelines, large national companies will simply drop the contract or refuse to buy. * Doctor Home: We provide custom problem-solving. Whether a seller needs a 12-month extended closing window, an upfront cash advance, help moving heavy items, or a leaseback agreement after closing, we tailor the agreement to the seller's specific life situation. 3. True Net Cash vs. Hidden Corporate "Deduction Fees" * National Brands: iBuyers frequently advertise "fair market offers" only to stack on a 5% to 12% "service fee," administrative fees, and aggressive repair deductions right before closing. * Doctor Home: Our offer is 100% transparent: $0 in commissions, $0 in service fees, and $0 in closing costs. What we offer is the exact dollar amount printed on your check at the title company. 4. Direct Accountability & Community Trust * National Brands: If an issue arises with an iBuyer or national franchisee, sellers get passed around a national call center or routed through customer service tickets. * Doctor Home: Sellers have direct line access to the business owners. Our reputation in St. Louis is tied to our name, which is why we handle every transaction with personal integrity and clear communication.

How do you walk a seller through the process the first time they speak with you?

When a homeowner reaches out to Doctor Home for the first time, my goal as a Home Buying Specialist isn't to deliver a high-pressure sales pitch—it’s to listen, understand their core problem, and build trust. Here is how I guide a seller step-by-step through our initial conversation: * 1. Setting a Pressure-Free Tone & Active Listening: I start by setting them at ease. I explain that our first chat is simply a discovery call to see if a cash sale actually makes sense for them. I ask about their timeline, their reasons for selling, and what an ideal outcome looks like for their family. * 2. Gathering Basic Property Details: We walk through the physical state of the home together. I ask about the property's general condition, major systems (roof, HVAC, foundation), and any immediate repairs needed, reassuring them that we buy homes strictly as-is and they don't need to clean or fix a thing. * 3. Explaining the Process & Transparency: I demystify how a cash sale works so there are no surprises. I outline our simple 3-step path: a quick property assessment, a transparent cash offer with zero commissions or hidden closing fees, and closing at a reputable local title company on the exact date they choose. * 4. Setting Clear Next Steps: If a cash offer aligns with their goals, we schedule a quick, convenient walkthrough of the property. If a cash sale isn't their best route, I'm completely honest about it and offer alternative guidance. By the end of that first call, the seller knows exactly what to expect, feels heard, and understands that they have complete control over the timeline and decision. Would you like to move on to the next survey question, or adjust any part of this response?

If a seller is shopping multiple cash offers, what should they actually be comparing beyond the headline number?

When a seller compares multiple cash offers, looking solely at the highest "headline" purchase price is one of the most common-and costly-mistakes they can make. In real estate, the highest price on paper rarely translates to the highest check at the closing table. Here are the critical factors sellers should evaluate beyond the purchase price: 1. Local Reputation & Direct Accountability * What to check: Is the buyer an established local business with verifiable community roots and reviews in St. Louis and St. Charles County, or an out-of-state entity/national call center? * Why it matters: A local investor who operates in your community relies on their local reputation, local title relationships, and verified reviews. If an issue arises during title work or closing, you can talk directly to the decision-maker. National entities or unverified online buyers can drop contracts without any local reputation fallout, leaving you stranded days before closing. 2. Earnest Money Deposit (EMD) & Non-Refundable Terms * What to check: How much cash is the buyer putting into escrow immediately, and when does it become non-refundable? * Why it matters: A buyer offering $250,000 with a $100 earnest deposit has zero real skin in the game. If they walk away 20 days later, you lose time and momentum for almost no compensation. A reputable buyer puts down a substantial deposit (e.g., $2,000 to $5,000+) held at an independent local title company. 3. Length & Rigor of the Inspection / Contingency Period * What to check: Does the contract include a 3- to 7-day inspection period or a 30-day "due diligence" window with a broad exit clause? * Why it matters: Wholesalers and predatory buyers use long inspection periods (14–30 days) as a safety net. They lock up your home, try to find an end buyer, and if they can't, they use a vague inspection contingency to cancel the contract or demand a $20,000 price reduction at the last minute. Look for short, defined inspection windows. 4. Net Payout vs. Hidden Deductions & Closing Costs * What to check: Who pays title insurance, escrow fees, transfer taxes, and administrative charges? Are there "service fees"? * Why it matters: Corporate iBuyers and national platforms often quote a high purchase price, but then subtract a 5% to 10% "service fee" alongside required repair credits right before closing. A lower gross offer that covers 100% of closing costs with zero hidden fees can easily net the seller more actual cash. 5. Direct Buyer vs. Unvetted Wholesaler ("And/Or Assigns") * What to check: Is the buyer purchasing the property themselves with their own capital, or are they assigning the contract to someone else? * Why it matters: Check the contract for the clause "and/or assigns." While assignment isn't inherently illegal, an unvetted wholesaler acts as a middleman. If they can't assign your contract for a profit, the deal collapses. Demand a recent Proof of Funds letter showing an actual liquid bank balance—not a generic pre-approval letter. 6. Flexible Closing Terms & Post-Closing Occupancy * What to check: Does the offer accommodate your exact moving timeline, or does it force you out on their schedule? * Why it matters: Terms often carry more financial value than a few thousand dollars in price. If an investor allows a 60-day closing window or a post-closing leaseback (letting you stay in the home after receiving your cash proceeds to transition comfortably), that saves thousands in temporary housing, double moves, and storage fees. Summary Checklist for Sellers | Feature | Strong Cash Offer | Weak / Predatory Offer | |---|---|---| | Local Presence | Established local presence & verified local reviews | Out-of-state call center / anonymous entity | | Earnest Deposit | $2,000 - $5,000+ | $10 - $100 | | Inspection Window | 3 - 7 Days | 14 - 30 Days | | Closing Costs | Buyer covers 100% | Seller pays or split | | Deductions / Fees | $0 fees | 5% - 10% "Service Fees" | | Proof of Funds | Bank statement / Proof of capital | Pre-approval letter / None |

The company representative’s account of their business, not an independent verification of its claims.

Offers & terms

Property type(s)
Single-family Land
Condition(s)
Any condition
Terms & perks
As-is Covers closing costs 7-day closings Rent-backs
Seller situations
Divorce Relocation Downsizing Inheritance Overdue mortgage Foreclosure Vacant homes Problem tenants Hoarding Fire damage

Where they buy

Choose a market to compare cash home buyers near you.

Chesterfield, MO Florissant, MO St Louis, MO Arnold, MO Ballwin, MO Clayton, MO Kirkwood, MO Ladue, MO Troy, MO Wildwood, MO

Ownership

Owner
Yully J. Matityahu
Founder
Jack Matityahu
Leadership
Ziv Goldfarb · Lea Avisar
Based in
St. Louis, MO
Founded
2023

Operations

Business type
Cash home buyer
Business model
Direct purchase
Ownership structure
Independent operator
Operating scale
St. Louis

Our ratings & analysis

94

Overall score

#1 of 26 similar

56 93
94

Doctor Home has an excellent overall score. It ranks 1st out of the 26 St. Louis, Missouri cash home buyers we’ve scored. It also ranks 1st out of the 60 Missouri cash home buyers we’ve scored. Excellent customer ratings are backed by a deep review history — 203 ratings averaging 5.0 stars. Recent customer ratings have held steady. Recent review activity is close to its lifetime average pace, with 27 reviews in the past 6 months. It has strong business credentials, including enhanced screening with our team.

Doctor Home vs. similar cash buyers

Swipe to compare

Metric This company
Doctor Home logo
Doctor Home
Overall score 94 92 90 87
Avg rating 5.0 (203 reviews) 4.8 (224 reviews) 4.8 (205 reviews) 4.8 (52 reviews)
Recent activity High High High High
Founded 2023 1926 2002 2020
BBB status Accredited, A+ Accredited, A+ Accredited, A+ Accredited, A+
Coverage Local Local Local Local
Company page Visit website Read review Read review Read review
95

Customer experience

Top 5% locally

Median 79
Avg rating 5.0
Total reviews 203
6-month rating 4.9
6-month trend Stable

Doctor Home has a strong customer experience profile. Its substantial review record was overwhelmingly positive. In the latest 3 months, the newest available average was slightly lower, but most recent ratings remained five-star. Its Customer Experience score of 95/100 places it around the top 1% of comparable cash buyers serving a single market.

Lifetime ratings. Lifetime feedback was strongly positive: 203 rated reviews averaged 5.0/5, with 197 five-star ratings. Reviews dated back to 2022. Our methodology adjusts small rating samples toward the typical company rating, then maps the adjusted rating to a score and applies a small review-depth deduction that decreases as the record grows. Volume credit grows with every rating, with an additional small adjustment that grows fastest over the first few hundred ratings and then slows. It strengthens the distance from the neutral, sample-adjusted 4.5-star signal; this record received a 0.78% adjustment to that signal. This added 0.19 score points before the depth deduction and confidence limit.

Recent ratings. Recent feedback remained strongly positive. Ratings averaged 4.9 across 48 reviews over 12 months, 4.9 across 27 reviews over 6 months and 4.8 across 8 reviews over 3 months, through November 1, 2026.

Rating trends. The 3-month average fell from 4.97 lifetime to 4.75 — down 0.22 stars, or 4.4%. The five-star share fell from 97.0% to 75.0%, down 22.0 percentage points. The average remained strongly positive: 6 of 8 ratings were five-star. The small sample limited confidence in a continuing trend.

Common themes. A smooth process led the feedback, appearing in 90 of 131 detailed customer reviews (69%), followed by fair pricing in 61 (47%) and fast closings in 53 (40%). Other common themes included honesty and transparency in 51 (39%). Reviews could mention multiple themes.

Review relevance. We classified 166 of 203 reviews (82%) as relevant to the home-selling experience. Another 13 concerned business partners, property buyers, another business and initial contacts without reported outcomes. The remaining 24 reviews had too little text to analyze. All 203 star ratings remained in the lifetime rating record.

89

Recent activity

Top 5% locally

Median 73
Recent reviews 27
Latest review 20 days ago
Recent pace 1.2×
Momentum Stable

Company activity · As of November 1, 2026 — our latest collection date.

Doctor Home has recent review activity. Its recent review volume is higher than similar companies, and its 6-month review pace is stable, at 1.2× its lifetime average pace. The company received fewer reviews in the latest 3 months — 8 reviews versus 19 reviews in the preceding 3 months. The company also completed enhanced screening with our team. Its Activity score of 89/100 places it around the top 4% of comparable cash buyers serving a single market.

Recent review volume. The company received more reviews than similar companies across all 3 periods. We counted 48 reviews over 12 months, 27 over 6 months and 8 over 3 months. Similar companies had median counts of 3, 1, and 0, respectively.

Recent review pace. Its 6-month review pace is stable, at 1.2× its lifetime average pace. Its latest 3-month pace was 0.7×, compared with 1× over 12 months. Recent rates averaged 4.5 reviews per month over 6 months, 2.7 over 3 months and 4 over 12 months, versus a lifetime average of 3.9. The record contains 203 reviews dating back to 2022. This gives the recent comparisons a substantial historical basis.

Review freshness. Its latest review on file was October 12, 2026 — less than 3 weeks old as of our last data refresh. 13% of all reviews appeared within the last 6 months, and the average review age was about 1.5 years.

Other business activity. Doctor Home claimed its directory profile and completed enhanced screening with our team. We have no business interview or reviewed purchase figure on file.

95

Credibility signals

Top 5% locally

Median 83
BBB status Accredited, A+
Verification status Enhanced
Reviews since 2022

Doctor Home has a very strong credibility profile. We identified the company’s leadership, business structure, and buying model, supported by a broad online presence. BBB lists 2023 as the business-start year. The main limits on its score were 4 years of documented review history and website depth and transparency. We found no specific legitimacy concerns or review-integrity red flags in the retained source material, so there were no deductions.

Verification. We identified Google, BBB, Yelp, and Trustpilot profiles. The BBB records we reviewed list accreditation since 2024. They list an A+ rating. Its Google Business Profile was verified. Doctor Home claimed its directory profile and completed enhanced screening with our team.

Website assessment. The website was accessible when checked on September 29, 2026. The website scored 95/100 for depth and transparency. It includes company background, team information, buying and service information, the process and terms, and customer testimonials or work examples.

Business details. We identified Jack Matityahu as the company’s founder and CEO. The BBB records we reviewed identify Yully J. Matityahu as managing member. BBB lists the business as an LLC. Its website identifies it as a direct buyer. No related businesses or DBAs were identified. The company says it sometimes finds another purchaser rather than buying directly. An investor describes buying a wholesale property from the company.

Track record. BBB lists October 26, 2023 as its business-start date, October 26, 2023 as its incorporation date, and November 27, 2022 as its profile-opening date. Reviews on file date back to July 6, 2022. Reviews appear in 34 of the 53 months covered by our records. The longest period without a recorded review was 17 months.

Complaints and red flags. No specific legitimacy concerns or review-integrity red flags were identified in the retained source material.

Verification checklist

5 of 5 baseline checks are supported by the evidence in our records.

Baseline checks

  • Business identity: Confirmed through Google Business Profile and BBB profile
  • Current business presence: Website accessible at last check; published phone number
  • Public feedback: 203 accepted third-party reviews
  • Established public history: Accepted review activity since 2022
  • Recent activity: 48 reviews in the recorded 12-month window; latest less than a month before collection

Additional verification

  • BBB status: Accredited, A+

Company-provided information

  • Claimed profile: The company claimed this profile
  • Enhanced screening: Company-reported business details received; not independently verified

Meeting these baseline checks is not a guarantee of current availability or a particular experience or transaction outcome. Compare offers, read reviews, and have a professional review any offers and contracts before moving forward.

Review explorer: Doctor Home

What reviewers say

131 substantive reviews Strong signal
Reviews most often praise Doctor Home for a smooth process, fair offers, and fast closings. We found no recurring negative pattern in the review text we analyzed.

Notable findings

  • 61 of 131 analyzed reviews (47%) mention fair offers, nearly 2x the typical rate for similar cash investors.
  • 90 of 131 analyzed reviews (69%) mention smooth process.
  • No recurring complaint pattern met our reporting threshold.

Reviews analyzed

203 public reviews

− 37 too short, irrelevant, or duplicate

− 35 relevant, but too general

131 detailed reviews with clear themes

Excluded: 13 outside the seller experience (e.g., business partners, home buyers); 24 with too little text to assess.

How reviews qualify

We identify themes from reviews that describe a specific experience with the service. General praise or criticism alone does not provide enough detail.

24 — No text or very short comments. No text or too little detail to assess the experience.

13 — Outside the experience assessed here. Reviews about something other than using the cash-offer or sell-fast service.

  • 4 — People buying a home, rather than selling
  • 1 — Too early to describe an experience
  • 7 — Vendors or business partners
  • 1 — A different company

35 — General feedback without specifics. Relevant reviews that give general praise or criticism without describing a specific experience.

Review themes

Positive feedback

Smooth process (90 reviews) 69%

90 reviews describe the process as easy, smooth, or straightforward.

Fair offers (61 reviews) 47%

61 reviews say the offer or overall deal felt fair.

Nearly 2x the typical rate
Fast closing (53 reviews) 40%

53 reviews mention a fast or on-schedule closing.

Honesty and transparency (51 reviews) 39%

51 reviews praise honesty, transparency, or following through on promises.

Communication (40 reviews) 31%

40 reviews praise communication or being kept informed.

Knowledge and professionalism (28 reviews) 21%

28 reviews describe the team as knowledgeable, capable, or professional.

Next steps if you’re considering Doctor Home

Even with a well-supported company record, the quality of an individual offer comes down to its price, terms, and the entity responsible for closing.

  1. Get the complete offer in writing

    Confirm the purchase price, closing date, seller-paid costs, inspection or cancellation rights, and whether the contract can be assigned to another buyer.

  2. Verify who is buying your home

    Confirm the legal business name, request proof of funds, and identify the title or closing company. If the brand has multiple offices, verify which office or entity is responsible for your offer.

  3. Compare the likely net proceeds

    Request at least 2 cash offers when possible. If time allows, compare them with an estimate of what you could net from an as-is listing after fees, repairs, and carrying costs.

How Clever Offers works
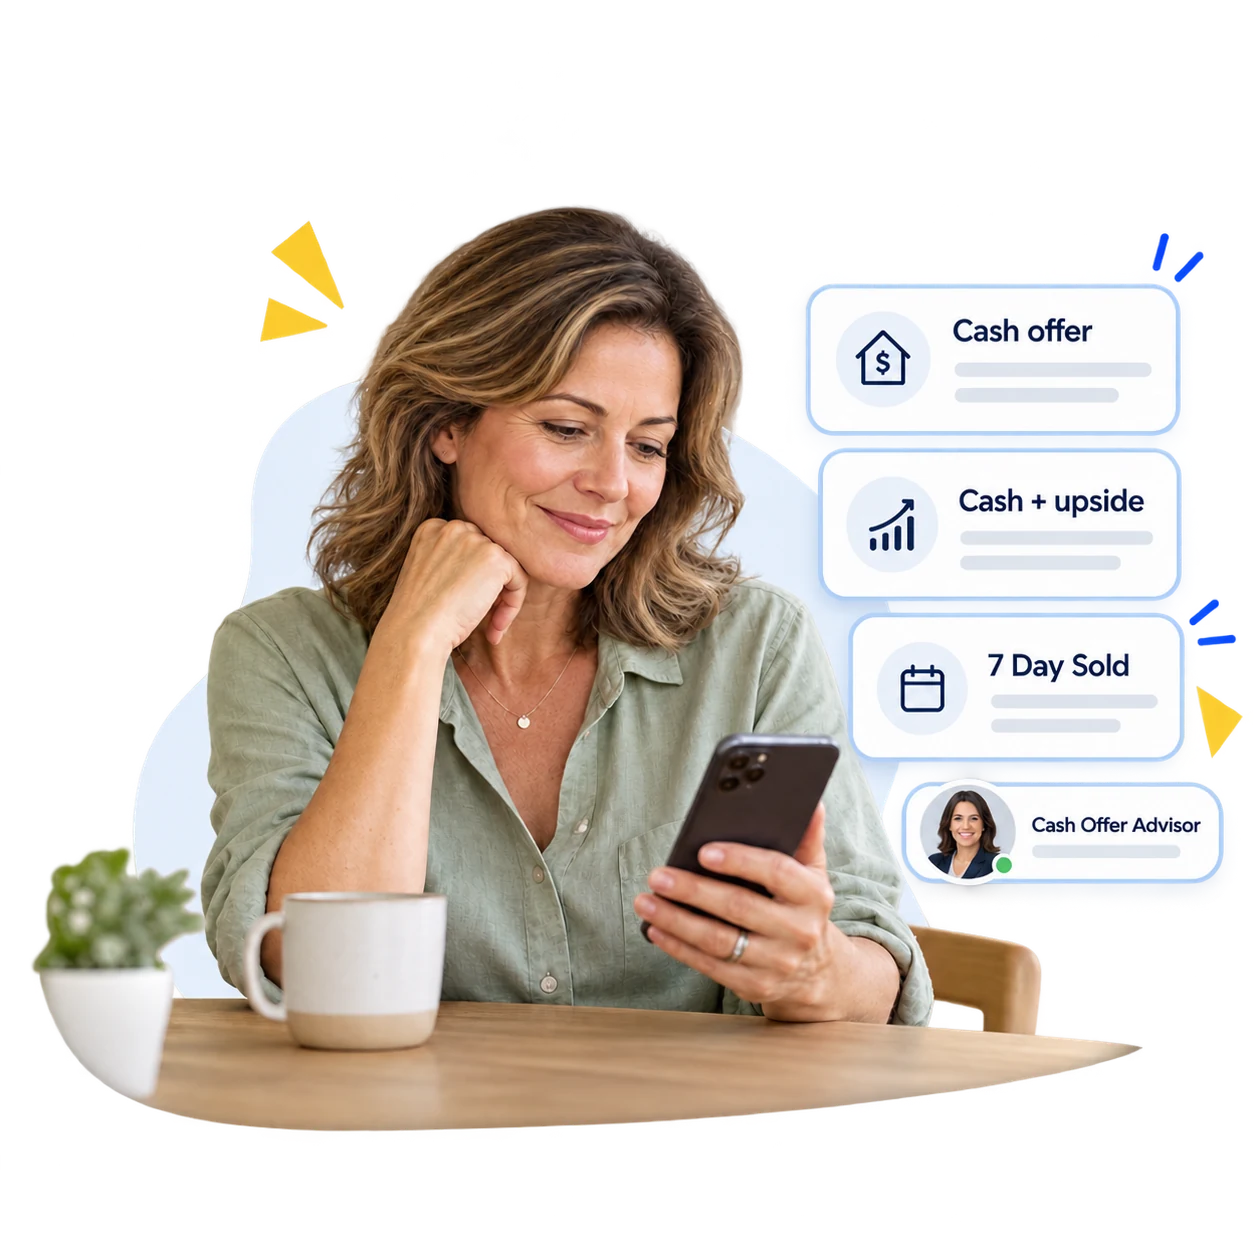
Illustration of a homeowner comparing Cash offer, Cash + upside, and 7 Day Sold options with a Cash Offer Advisor
  1. Tell us about your home

    Share your property details and timeline. We find cash investors and other sell-fast solutions that fit your needs.

  2. Compare your offers

    Compare multiple cash offers alongside options like 7 Day Sold. Your Cash Offer Advisor helps you understand pricing, timing, and terms.

  3. Sell on your terms

    Choose your best fit and close on your timeline — or decline the offers. Requesting offers is always free, with no obligation or pressure.

Related guides and resources
How we researched and scored this company

Methodology

We research each company using its website, business profiles, and third-party customer reviews. We use company sources to understand its services and terms, and distinguish those claims from independent evidence. When available, we also draw on interviews with company representatives and sellers, and relevant public records.

When there is enough evidence, we calculate an overall score out of 100 using 3 categories:

  • Customer experience (67.5%) reflects customer satisfaction, based primarily on average customer ratings and the number of reviews supporting them.
  • Recent activity (20%) reflects recent review volume, how recently the company received a review, and how its recent review pace compares with its history. Reviews are a signal of activity, not a count of completed home purchases.
  • Credibility (12.5%) considers business verification, website transparency, public engagement, and documented operating history.

Use the company or location identified on this page when interpreting the evidence. A broader company record may not describe every local office. Review history is separate from the company’s founding date.

Limited evidence can restrict what we can assess. A company may appear without a score, and a small review sample may not represent a typical seller’s experience. Scores summarize the evidence available to us; they do not predict an offer price or guarantee a sale or service quality.

Sources

  1. Company website, website information up to date as of September 2, 2026; website content analysis completed September 3, 2026.
  2. Better Business Bureau, profile information up to date as of September 3, 2026; review data up to date as of September 3, 2026; complaint data up to date as of September 3, 2026; reviews checked for updates on November 1, 2026.
  3. Google, profile information up to date as of October 21, 2026; review data partially collected on October 21, 2026; reviews checked for updates on October 21, 2026.
  4. TrustPilot, review data up to date as of February 11, 2026; reviews checked for updates on October 19, 2026 (no new reviews).
  5. Enhanced screening.
  6. Jack Woolf, Jack Woolf · Ceo · Doctor home, written interview.