Maryland Cash Home Buyers: Review & Ratings (November 2026)
Written by Jamie Ayers +2 others
Edited by Andrew Whytock Reviewed by Ben Mizes
Written by Jamie Ayers Edited by Andrew Whytock Reviewed by Ben Mizes
Updated November 2, 2026
Property Investor
Property investor Direct buyer

Maryland Cash Home Buyers

Maryland Cash Home Buyers earns a modest overall score. It has perfect customer ratings from a small review record, along with strong business credentials.

Overall score

#371 of 456 similar

At a glance

Profile status
Enhanced
Avg rating
5.0 (10 reviews)
BBB status
Not accredited, A-
Founded in
2020

About

Maryland Cash Home Buyers buys across Maryland and the Washington, DC, area. Sellers can choose a direct cash sale or explore a listing with an agent partner. Direct cash sellers can skip repairs and cleaning.

Read the full bio

Owner Q&A

“First, identify who is signing the contract, whether that party intends to purchase the property or assign the agreement, and whether closing depends on finding another buyer.”

Justin Mitchell Justin Mitchell · Founder & Principal Home Buyer · Maryland Cash Home Buyers (MCHB)
Read the full interview

Offers & terms

Buys:
Single-family Multifamily Condos Townhomes
Terms:
As-is Covers closing costs 7-day closings Flexible closing
Situations:
Divorce Relocation Downsizing Inheritance
See service details

Score breakdown

Customer experience Limited depth
Recent activity No activity
Credibility signals Solid trust signals
View full breakdown

Is Maryland Cash Home Buyers legit?

Not enough data. We don’t yet have enough independently verified information to make a confident assessment of Maryland Cash Home Buyers. We found some evidence that it is an operating business, but its public record is too limited for us to complete our usual verification checks.

View verification checklist

Compare similar cash home buyers

In-network investor
90

Ace Homebuyers

Maryland cash buyer. Leave unwanted items; standard closing costs covered.

Read review
Property investor
90

Home Buyers Express

Baltimore cash buyer. Sellers can close at home or at their attorney’s office.

Read review
Buy before you sell
83

Flyhomes

Access your home equity and financing to buy your next home before selling.

Read review
iBuyer
75

Opendoor

Sell your home directly for cash, with optional additional proceeds after resale.

Read review

About Maryland Cash Home Buyers

Company bio

Maryland Cash Home Buyers is based in Frederick and buys homes throughout Maryland and the Washington, DC, area. It's been in business since 2020. Justin Mitchell founded and owns the business. Sellers can choose a direct cash sale or explore a listing with its agent partner, Debbi Rivero. The company says she's a licensed Maryland Realtor with over 30 years of local real estate experience.

It buys individual rentals and portfolios with tenants in place, without requiring eviction before sale. Direct cash sellers can skip repairs, cleaning, and staging and pay no agent commissions. In most transactions, the company also covers standard closing costs. You choose the closing date.

Owner Q&A

Justin Mitchell

Justin Mitchell · Founder & Principal Home Buyer · Maryland Cash Home Buyers (MCHB)

Justin Mitchell of Maryland Cash Home Buyers (MCHB) discusses the company’s buying process, how it makes offers, closing timelines, and advice for homeowners considering a cash sale.

Owner Q&A

Justin Mitchell · Justin Mitchell · Founder & Principal Home Buyer · Maryland Cash Home Buyers (MCHB)

How fast can you close if a seller needs a quick exit?

When a seller responds promptly, the property has clear title, and the title company has immediate availability, we can target closing in as little as 21 days from the date the signed purchase agreement is delivered to the title company. That allows time for title work, due diligence, payoff information, and settlement documents. The actual closing date depends on title readiness, property access, required documentation, and any liens, probate matters, or other complications.

What types of properties do you typically buy? (distressed, inherited, tenant-occupied, any condition, etc.)

We typically buy single-family homes, townhouses, condominiums, and small multifamily properties in as-is condition. That includes inherited, vacant, tenant-occupied, outdated, fire- or water-damaged properties and homes requiring major repairs or involving time-sensitive circumstances. We do not assume every property should follow the same fix-and-flip model. Depending on the property and market, MCHB may renovate and resell it, hold it as a rental, or pursue a redevelopment and new-construction strategy. Through the MCHB Dual-Path Solution™, we can also help a homeowner compare a direct cash purchase with a licensed Realtor® consultation when an open-market listing may better serve the seller. Redevelopment & Builder Purchase Program™: For older homes on larger or well-located lots with builder/developer redevelopment potential; currently available for qualifying properties in Montgomery County, with additional Maryland markets planned.

Is there room to negotiate, or is your first number typically the final number?

There is room to negotiate, but our first number is intended to be our best supportable offer—not an opening tactic. Under our Fair Offer Promise™, we do not start artificially low expecting a seller to haggle, and we do not knowingly start high to secure a contract and then plan a last-minute price reduction.

Sellers are welcome to counter. Comparable sales, repair information, or other property facts are especially helpful, but we will reconsider our assumptions even if the seller simply believes we missed important context. If due diligence later reveals a material issue, any proposed adjustment should be explained and supported—not sprung on the seller at closing.

If a traditional cash price cannot meet the seller’s goals, the MCHB Dual-Path Solution™ may provide a Realtor® listing alternative, while our Creative Equity Partnership™ may support a higher price through mutually beneficial terms. Our objective is an accurate, understandable offer from the beginning—not a pricing game.

What's the typical timeline from accepted offer to closing?

Our typical target is approximately 30 days from a ratified purchase agreement to closing. The exact timeline can vary depending on title readiness, property access, due diligence, mortgage payoffs, liens, probate requirements, or other circumstances affecting the transaction. We establish the expected closing date in writing and keep the seller informed if an issue requires additional time.

Roughly how many homes does your company buy in a typical month or year?

We typically participate in approximately 10–15 residential real estate transactions annually, although the number varies with market conditions and whether a property is a suitable fit. We intentionally handle a limited number at a time so I can remain directly involved in the property evaluation, transaction structure, offer terms, and seller communication.

Is there a type of seller you'd advise NOT to take your offer? Who, and why?

Yes. I would advise a homeowner not to accept our cash offer when a conventional listing is reasonably expected to produce meaningfully higher net proceeds and the seller has the time, money, ability, and risk tolerance required to prepare and market the property successfully.

If they are comfortable managing repairs, staging, showings, inspections, buyer financing, carrying costs, and a longer or less certain timeline, listing may be the better financial choice. Through the MCHB Dual-Path Solution™, we can connect that homeowner with a licensed Maryland Realtor® consultation rather than encourage them to accept a cash offer that does not best serve their priorities.

What advice would you give a homeowner who's considering a cash buyer for the first time?

Do not evaluate the offer solely by its headline price. First, identify who is signing the contract, whether that party intends to purchase the property or assign the agreement, and whether closing depends on finding another buyer. Assignment is not automatically a problem, but the buyer should explain the structure honestly.

Most importantly, ask how the offer was calculated. A credible buyer should be able to support the price with comparable sales, property-condition assumptions, estimated costs, or another legitimate strategy—not simply quote the number most likely to win the contract and worry about making it work later.

Compare the offer’s actual net proceeds, contingencies, deposit, cancellation rights, and closing terms with a realistic listing alternative. Read the entire agreement and, when appropriate, have an attorney or licensed real estate professional review it before signing.

There's a reputation problem in the 'We Buy Houses' industry — what's fair about that reputation, and what's overblown?

A reputable cash buyer makes the transaction understandable. The buyer should explain the valuation, identify the purchasing party, provide credible proof of funds or a clear funding plan, use a reputable title company, disclose fees and material contract terms, and give the seller time to review the agreement. Red flags include high-pressure tactics, vague offer calculations, hidden charges, weak deposits, broad cancellation rights, unclear assignment language, or unsupported price reductions late in the transaction.

One frequently overlooked warning is an all-cash offer suspiciously close to an automated estimate or the anticipated as-is FMV listing price despite the property’s repairs and the buyer’s acquisition, holding, and resale costs. A high offer can be legitimate when supported by redevelopment value or creative terms, but the buyer should be able to document why the number works and what could cause it to change. Whether an inflated offer results from poor underwriting or a deliberate tactic, the seller faces the same risk: losing valuable time under contract before being asked to accept a substantially lower price.

How transparent are you with sellers about how you arrived at the offer?

Transparency is central to our process. Under our open-book Fair Offer Promise™, the seller receives a written offer or property review documenting the comparable sales, property-condition assumptions, estimated value, repairs, acquisition, renovation, holding and resale costs, and the investment margin used to calculate our offer.

We then compare the cash-sale proceeds with the seller’s estimated net proceeds from an as-is or renovated listing after commissions, repairs, carrying costs, concessions, and other selling expenses. For a redevelopment offer, our private property review also examines relevant land and teardown sales, nearby new construction, lot characteristics, zoning, and builder demand.

Our Maryland Seller Bill of Rights™—an internal company code of ethics, not state legislation—commits us to open-book pricing, no hidden fees, and no-pressure options. The goal is for sellers to understand the proceeds, costs, timeline, work, and risks of each path before deciding.

Can you accommodate sellers who need more time — say, 60 or 90 days? What's the longest closing window you've offered?

Yes. We can generally accommodate 60- or 90-day closing timelines and, when appropriate, schedule a closing as far as six months out. If a homeowner is more than six months away from being ready, we typically avoid tying them to an unnecessarily long contract. Instead, we schedule a follow-up in our system and reconnect closer to their preferred selling date. The goal is to fit the seller’s actual timeline rather than pressure them into closing sooner than necessary.

Tell us about your company — how long have you been buying homes for cash, what markets do you operate in, and what's your role?

Maryland Cash Home Buyers (MCHB) has been buying homes for cash throughout Maryland since 2020. As the company’s founder and principal home buyer, I oversee property evaluations, underwriting, offer structure, and seller communication from the initial conversation through closing. I also help homeowners compare a direct cash sale with other realistic options, including a licensed Maryland Realtor® consultation when an open-market listing may better serve their goals.

Walk us through how you arrive at an offer. What's the methodology?

Our open-book Fair Offer Promise™ begins with recent comparable sales, the property’s current condition, and its estimated after-repair value. We then account for repairs, financing and holding costs, resale and closing expenses, market risk, and the investment margin needed for the purchase to work. We show the seller the major assumptions rather than presenting an unexplained number.

Through the MCHB Dual-Path Solution™, we also estimate what the homeowner might net from an as-is or renovated Realtor® listing after commissions, repairs, concessions, carrying costs, and other selling expenses. When a property may qualify for our Redevelopment & Builder Purchase Program™, we additionally examine the lot, location, zoning, redevelopment potential, nearby new construction, and relevant builder demand.

The seller can then compare the likely net proceeds, timeline, work, and risk associated with a traditional cash offer, a redevelopment-focused cash offer when available, and an open-market listing before choosing the path that best fits their priorities.

When does selling to a cash buyer genuinely make sense, and when does it not?

Selling to a cash buyer genuinely makes sense when the seller values speed, certainty, privacy, and convenience enough to accept potentially lower proceeds. It can be especially practical when a property needs substantial repairs, has tenants, was inherited, faces a deadline, or the homeowner does not want to manage renovations, staging, showings, inspections, financing contingencies, and months of uncertainty.

The correct comparison is not the cash offer versus the anticipated listing price. It is the seller’s expected net proceeds from each option after repairs, commissions, concessions, carrying costs, closing expenses, and risk—along with the time and work each path requires.

A cash sale may not make sense when the property is market-ready, the seller has sufficient time and flexibility, and broad market exposure is likely to produce meaningfully higher net proceeds. The seller should also verify the buyer’s credibility and contract terms. Through the MCHB Dual-Path Solution™, we compare these factors so the homeowner can choose the option that best fits their financial and personal priorities.

Who is your typical seller? Walk us through the situations that bring people to your door.

There is no single “typical” seller, and not everyone who contacts us is in financial distress. Most are dealing with a property condition, life transition, or deadline that makes a conventional listing less practical. That may involve an inherited or probate property, expensive repairs, structural problems, an unwanted rental with tenants, vacancy, foreclosure risk, divorce, relocation, downsizing, or simply wanting a private sale without repairs, staging, or repeated showings.

Through our Redevelopment & Builder Purchase Program™, we also speak with longtime owners of older homes on larger or well-located Montgomery County lots who want to understand whether the property’s land and redevelopment potential could be more valuable than renovating the existing house.

The common thread is that these homeowners need a clear comparison of their realistic options. We help them evaluate an as-is cash sale, a possible builder or redevelopment sale, and an open-market listing based on likely net proceeds, timing, risk, and the work required. Sometimes a cash sale is the right fit; in other cases, a licensed Realtor® consultation may better serve the homeowner.

How do you differentiate yourself from national brands (Opendoor, We Buy Ugly Houses, HomeVestors)?

The biggest difference is that MCHB does not begin with a single predetermined product. National buyers generally place sellers into an established cash-offer or corporate program. Opendoor now offers more than a traditional cash purchase, while We Buy Ugly Houses and HomeVestors operate through independently owned franchise offices, but neither model is equivalent to our comprehensive, locally managed MCHB Dual-Path Solution™.

I work directly with each homeowner to determine which structure best fits the property and the seller’s priorities. That may include an as-is cash purchase, a licensed Maryland Realtor® consultation, mutually beneficial terms through our Creative Equity Partnership™, or, for qualifying Montgomery County properties, a builder-focused cash option through our Redevelopment & Builder Purchase Program™.

Our open-book Fair Offer Promise™ also documents the valuation assumptions, estimated costs, and likely net proceeds so the seller can compare the available paths. MCHB’s advantage is not that we automatically pay more; it is that we combine local decision-making, direct accountability, transparent underwriting, and multiple sale strategies instead of forcing every seller into the same solution.

How do you walk a seller through the process the first time they speak with you?

I first learn the seller’s goals, property condition, price expectations, and preferred timeline. I then explain the MCHB Dual-Path Solution™: an as-is cash purchase or a licensed Realtor® consultation when listing may produce a better outcome.

If the seller’s price exceeds what a traditional cash purchase supports but they cannot or prefer not to list, our Creative Equity Partnership™ may use mutually beneficial terms to support a higher price. For qualifying older homes on larger or well-located Montgomery County lots, our Redevelopment & Builder Purchase Program™ may provide a builder-focused cash option based partly on redevelopment potential.

We then use our open-book Fair Offer Promise™ to explain the valuation, estimated repairs, holding and selling costs, and how we arrived at the offer so the seller can compare the tradeoffs and decide without pressure.

If a seller is shopping multiple cash offers, what should they actually be comparing beyond the headline number?

Sellers should compare the expected net proceeds and the probability that each offer will actually close at the stated price. Review any fees, closing-cost obligations, deposit amount, due-diligence period, cancellation rights, price-adjustment provisions, closing timeline, and proof of funds.

They should also determine who the contracting buyer is, whether that buyer intends to purchase the property or assign the contract, and whether closing depends on finding another investor. Assignment is not inherently improper, but the structure and risks should be disclosed clearly.

An unusually high offer is not necessarily the best offer. Sellers should ask how the buyer calculated it and what could cause it to change. A credible, well-supported offer with clear terms may be more valuable than a higher headline number that ties up the property and is later reduced or canceled.

The company representative’s account of their business, not an independent verification of its claims.

Offers & terms

Property type(s)
Single-family Multifamily Condos Townhomes
Condition(s)
Any condition
Terms & perks
As-is Covers closing costs 7-day closings Flexible closing
Seller situations
Divorce Relocation Downsizing Inheritance Probate Foreclosure Liens Problem tenants Hoarding Water damage Holdover tenants

Where they buy

Choose a market to compare cash home buyers near you.

Ownership

Owners
Justin Mitchell · Debbi Rivero
Based in
Frederick, MD
Founded
2020

Operations

Business type
Cash home buyer
Business model
Direct purchase
Ownership structure
Independent operator
Operating scale
Statewide in MD + local areas

Our ratings & analysis

68

Overall score

#371 of 456 similar

52 92
68

Maryland Cash Home Buyers has a mixed overall score, mainly because there’s little customer feedback to work with. All 10 ratings we have are 5-star. Its strong business credentials include an A- BBB rating. We have no reviews from the past 6 months, leaving less insight into current customer experience. That doesn’t establish that the company has stopped buying homes.

Maryland Cash Home Buyers vs. similar cash buyers

Swipe to compare

Metric This company
Maryland Cash Home Buyers logo
Maryland Cash Home Buyers
Overall score 68 90 90 89
Avg rating 5.0 (10 reviews) 4.9 (49 reviews) 5.0 (110 reviews) 4.8 (134 reviews)
Recent activity None High Medium High
Founded 2020 2021 2011 2016
BBB status Not accredited, A- Accredited, A+ Accredited, A+ Accredited, A+
Coverage Multi-state Multi-state Local Statewide
Company page Visit website Read review Read review Read review
70

Customer experience

Bottom 50% in US

Median 83
Avg rating 5.0
Total reviews 10
18-month rating 5.0
18-month trend Not enough evidence

Maryland Cash Home Buyers has a generally positive customer experience profile. Every rating in its lifetime review record was five-star. The main limit was review depth: 10 ratings provided limited evidence. No new ratings appeared in the latest 6 months, limiting what we could assess about current experiences. Its Customer Experience score of 70/100 places it below the middle of comparable cash buyers serving multiple markets.

Lifetime ratings. Lifetime feedback was uniformly positive: 10 rated reviews averaged 5.0/5, all five-star. Reviews dated back to 2025. Our methodology adjusts small rating samples toward the typical company rating, then maps the adjusted rating to a score and applies a small review-depth deduction that decreases as the record grows. Volume credit grows with every rating, with an additional small adjustment that grows fastest over the first few hundred ratings and then slows. It strengthens the distance from the neutral, sample-adjusted 4.5-star signal; this record received a 0.05% adjustment to that signal. This added 0.01 score points before the depth deduction and confidence limit. The confidence limit also constrained the score.

Recent ratings. No new ratings appeared over the latest 12, 6 or 3 months, through October 18, 2026. There was no recent rating evidence to assess.

Rating trends. We did not have enough comparable lifetime and recent rating data to assess a trend.

Common themes. A smooth process led the feedback, appearing in 8 of 10 detailed customer reviews (80%), followed by fast closings in 5 (50%). Reviews could mention multiple themes.

Review relevance. We classified 10 of 10 reviews (100%) as relevant to the home-selling experience. All 10 star ratings remained in the lifetime rating record.

51

Recent activity

Bottom 50% in US

Median 66
Recent reviews 0
Latest review 14 months ago
Recent pace —
Momentum —

Company activity · As of October 18, 2026 — our latest collection date.

Maryland Cash Home Buyers has documented business activity, but its recent review record is quiet. Its records include completed enhanced screening. The main limit is the absence of new reviews over the past 6 months. Its Activity score of 51/100 ranks #374 of 456 comparable cash buyers serving multiple markets.

Recent review volume. The company received fewer reviews than similar companies across all 3 periods. We counted 0 reviews over 12 months, 0 over 6 months and 0 over 3 months. Similar companies had median counts of 5, 2, and 1, respectively.

Recent review pace. No new reviews appeared over the latest 6 months, so we leave its pace classification unassessed. Its 6- and 3-month rates were 0× its lifetime average pace, compared with 0× over 12 months. Recent rates averaged 0 reviews per month over 6 months, 0 over 3 months and 0 over 12 months, versus a lifetime average of 0.5. The record contains 10 reviews dating back to 2025.

Review freshness. The review record lacks recent feedback. Its latest review on file was August 15, 2025 — more than 1 year old as of our last data refresh. No reviews appeared within the last 6 months, and the average review age was about 1.5 years.

Other business activity. Maryland Cash Home Buyers claimed its directory profile and completed enhanced screening with our team. We have no business interview or reviewed purchase figure on file.

86

Credibility signals

Top 50% in US

Median 86
BBB status Not accredited, A-
Verification status Enhanced
Reviews since 2025

Maryland Cash Home Buyers has a strong credibility profile (#25 of 51 in MD). We identified the company’s leadership and buying model, supported by a broad online presence. The company reports operating since 2020 on its website. The main limits on its score were 1 year of documented review history, unconfirmed business structure, and website depth and transparency. We found no specific legitimacy concerns or review-integrity red flags in the retained source material, so there were no deductions.

Verification. We identified Google, BBB, and Yelp profiles. The BBB records we reviewed list the profile as not accredited. They list an A- rating. Its Google Business Profile was verified. Maryland Cash Home Buyers claimed its directory profile and completed enhanced screening with our team.

Website assessment. The website was accessible when checked on September 29, 2026. The website scored 90/100 for depth and transparency. It includes company background, team information, buying and service information, the process and terms, and customer testimonials or work examples.

Business details. We identified Justin Mitchell as the company’s owner and founder. We could not confirm its business structure. Its website identifies it as a direct buyer. No related businesses or DBAs were identified. Its website names Debbi Rivero as expert partner and in-house advisor.

Track record. Maryland Cash Home Buyers reports operating since 2020 on its website. BBB lists May 7, 2025 as its profile-opening date. Reviews on file date back to March 9, 2025. Reviews appear in 2 of the 20 months covered by our records. Review activity is intermittent.

Complaints and red flags. No specific legitimacy concerns or review-integrity red flags were identified in the retained source material.

Verification checklist

3 of 5 baseline checks are supported by the evidence in our records.

Baseline checks

  • Business identity: Confirmed through Google Business Profile and BBB profile
  • Current business presence: Website accessible at last check; published phone number
  • Public feedback: 10 accepted third-party reviews
  • Established public history: Public review history has not yet reached 2 years
  • Recent activity: Latest recorded review: about 1 year before collection

Additional verification

  • BBB status: A-

Company-provided information

  • Claimed profile: The company claimed this profile
  • Enhanced screening: Company-reported business details received; not independently verified

This does not mean the company is illegitimate. It means our current sources do not provide enough evidence for a confident assessment. Verify its legal business name and proof of funds, and compare its offer before signing anything.

Review explorer: Maryland Cash Home Buyers

What reviewers say

10 substantive reviews Weak signal
Reviews most often praise Maryland Cash Home Buyers for a smooth process, and fast closings.

Notable findings

  • 8 of 10 analyzed reviews (80%) mention smooth process.

Reviews analyzed

10 public reviews

− 0 relevant, but too general

10 detailed reviews with clear themes

No reviews were removed by the initial filters.

How reviews qualify

We identify themes from reviews that describe a specific experience with the service. General praise or criticism alone does not provide enough detail.

Review themes

Positive feedback

Smooth process (8 reviews) 80%

8 reviews describe the process as easy, smooth, or straightforward.

Fast closing (5 reviews) 50%

5 reviews mention a fast or on-schedule closing.

Next steps if you’re considering Maryland Cash Home Buyers

Our information is limited. Verify the buyer and the written offer before you commit.

  1. Get the complete offer in writing

    Confirm the purchase price, closing date, seller-paid costs, inspection or cancellation rights, and whether the contract can be assigned to another buyer.

  2. Verify who is buying your home

    Confirm the legal business name, request proof of funds, and identify the title or closing company. If the brand has multiple offices, verify which office or entity is responsible for your offer.

  3. Compare the likely net proceeds

    Request at least 2 cash offers when possible. If time allows, compare them with an estimate of what you could net from an as-is listing after fees, repairs, and carrying costs.

How Clever Offers works
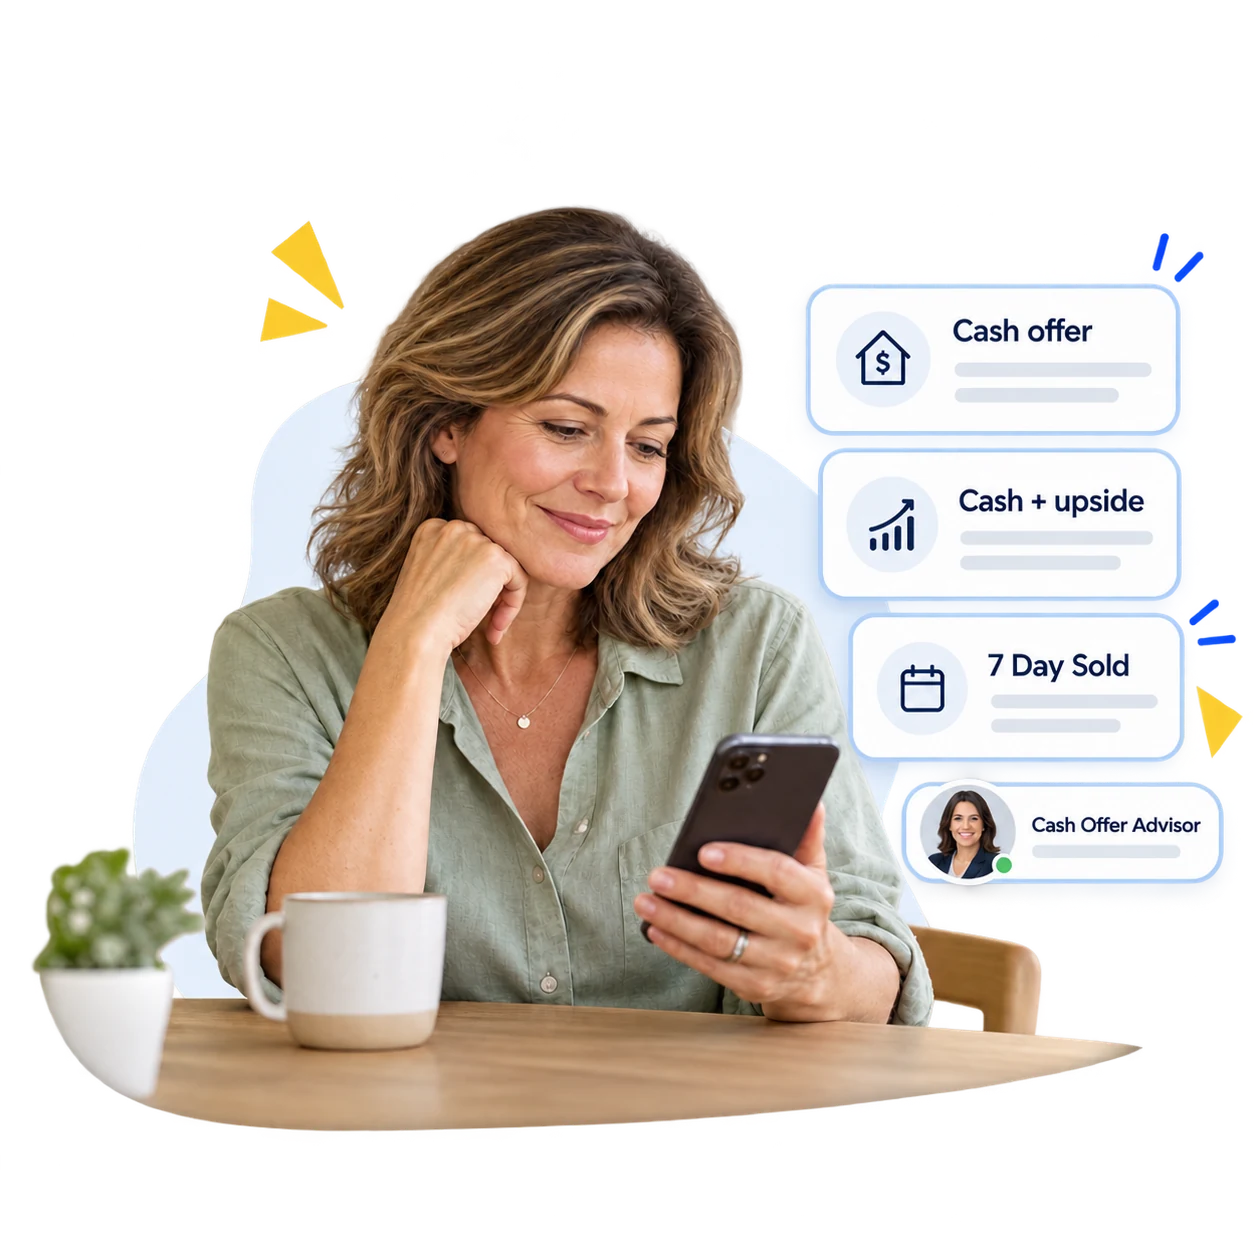
Illustration of a homeowner comparing Cash offer, Cash + upside, and 7 Day Sold options with a Cash Offer Advisor
  1. Tell us about your home

    Share your property details and timeline. We find cash investors and other sell-fast solutions that fit your needs.

  2. Compare your offers

    Compare multiple cash offers alongside options like 7 Day Sold. Your Cash Offer Advisor helps you understand pricing, timing, and terms.

  3. Sell on your terms

    Choose your best fit and close on your timeline — or decline the offers. Requesting offers is always free, with no obligation or pressure.

Related guides and resources
How we researched and scored this company

Methodology

We research each company using its website, business profiles, and third-party customer reviews. We use company sources to understand its services and terms, and distinguish those claims from independent evidence. When available, we also draw on interviews with company representatives and sellers, and relevant public records.

When there is enough evidence, we calculate an overall score out of 100 using 3 categories:

  • Customer experience (67.5%) reflects customer satisfaction, based primarily on average customer ratings and the number of reviews supporting them.
  • Recent activity (20%) reflects recent review volume, how recently the company received a review, and how its recent review pace compares with its history. Reviews are a signal of activity, not a count of completed home purchases.
  • Credibility (12.5%) considers business verification, website transparency, public engagement, and documented operating history.

Use the company or location identified on this page when interpreting the evidence. A broader company record may not describe every local office. Review history is separate from the company’s founding date.

Limited evidence can restrict what we can assess. A company may appear without a score, and a small review sample may not represent a typical seller’s experience. Scores summarize the evidence available to us; they do not predict an offer price or guarantee a sale or service quality.

Sources

  1. Company website, website information up to date as of September 2, 2026; website content analysis completed September 4, 2026.
  2. Better Business Bureau, profile information up to date as of September 3, 2026; complaint data up to date as of September 3, 2026.
  3. Google, profile information up to date as of October 18, 2026; review data up to date as of January 9, 2026; reviews checked for updates on October 18, 2026 (no new reviews).
  4. Enhanced screening.
  5. Justin Mitchell, Justin Mitchell · Founder & Principal Home Buyer · Maryland Cash Home Buyers (MCHB), written interview.